Your Local Mortgage Lender
Located in Yukon, Oklahoma
Meet Chris Barnes
I'm Chris Barnes, and for more than 25 years, my team and I have helped people navigate home financing with clear answers, honest advice, and a plan that fits their lives.
Whether you're buying, refinancing, or building, we take the time to understand what matters to you and explain your options so you feel confident moving forward. Our job goes beyond finding a loan: it's helping you choose a mortgage strategy that makes sense today and supports your goals down the road.
If you're a real estate agent or referral partner, you can count on me and the Barnes Mortgage Team to communicate, stay involved, and care for the people you send our way.
As a husband, dad, and "Poppy," I understand how much the right home means to a family. I'd love the opportunity to get to know you, answer your questions, and earn your trust.
Chris Barnes
Mortgage Loan Originator, NMLS #1179666 · Novus Home Mortgage · Yukon, Oklahoma
Personalized Mortgage Experience
Chris Barnes offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Yukon, Oklahoma.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Non-QM / Portfolio Loans
DSCR Loans
Bank Statement Loans
Renovation Loans
Down Payment Assistance Programs
Refinance Loans
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
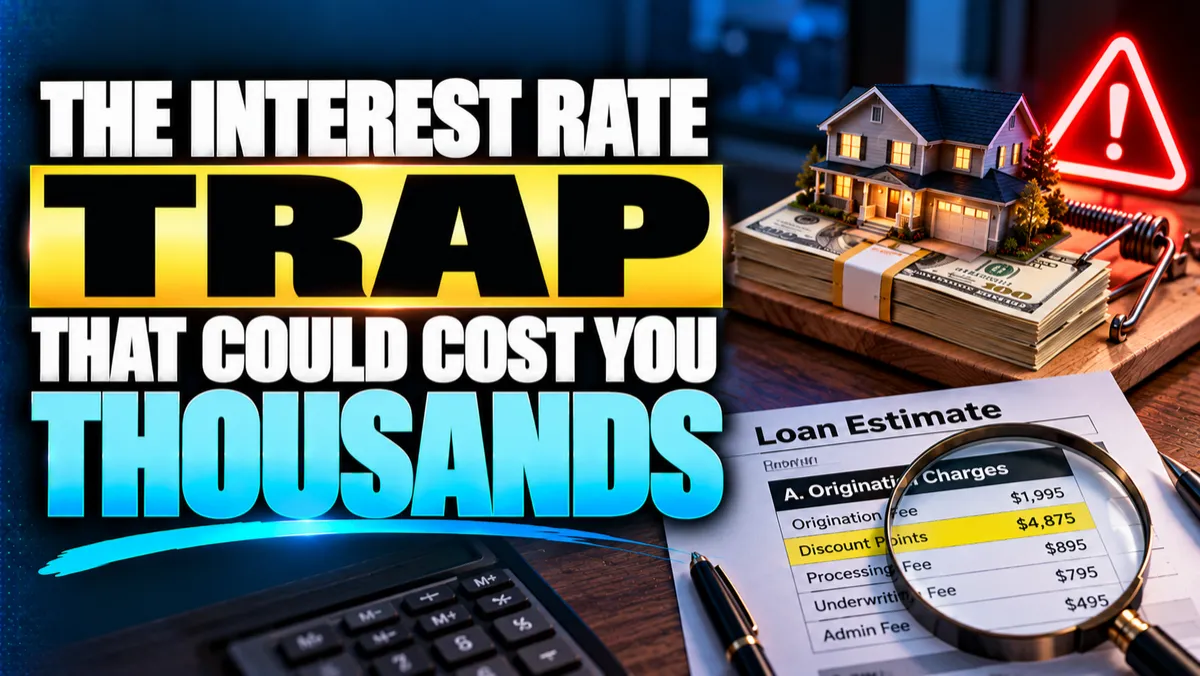
The Lowest Mortgage Rate Is Not Always the Best Loan and Here Is Where Buyers Lose Thousands
The Trap That Catches Buyers Who Are Only Looking at the Rate
If you are shopping for a mortgage and asking lenders only for their lowest interest rate you may be walking directly into the most expensive decision in the transaction. Chris Barnes wants buyers to understand what is actually behind an advertised rate before any commitment is made based on that number.
Why Lenders Lead With the Lowest Rate
The lowest rate stops the scroll. Lenders know this and they use it. What they do not always advertise upfront is the cost required to achieve that number. Discount points paid at closing buy the rate down and each point represents one percent of the loan amount paid out of pocket at closing. On a four hundred thousand dollar loan one point is four thousand dollars. Two points is eight thousand.
Beyond discount points there can be origination charges and fees embedded in the loan structure that increase the total cost of obtaining the financing without being immediately visible in the rate comparison. The loan that looks most attractive in the initial conversation may be the most expensive when the full picture is examined.
The Break-Even Problem Nobody Explains
Paying points to buy down the rate only makes financial sense if you stay in the loan long enough for the monthly savings to recover the upfront cost. If the monthly payment is fifty dollars lower because of a rate buydown it takes two hundred months to break even on ten thousand dollars paid at closing. If you refinance or sell before reaching that point the money spent on points is simply gone with no financial benefit to show for it.
This is the question most buyers never think to ask and most lenders do not volunteer the answer to. What is the actual break-even timeline on the points being paid? The answer to that question tells you whether the rate structure being offered serves your situation or the lender’s revenue.
Where to Look on the Loan Estimate
The loan estimate is the standardized document every lender is required to provide and it contains the information needed to make this comparison accurately. Page two is where the detail lives. Section A shows origination charges and points. Those numbers reveal the true cost of obtaining the rate being quoted.
Comparing loan estimates from multiple lenders using section A alongside the rate gives a complete picture of total borrowing costs rather than a single number that can be manufactured to look attractive while hiding the real expense elsewhere in the structure.
What Smart Financing Actually Looks Like
Smart financing is not about finding the lowest rate on a comparison website. It is about understanding total borrowing costs, knowing how the loan structure fits your actual timeline and plans, and aligning the financing with your long-term wealth strategy rather than optimizing for a number that looks good today and costs you money over time.
Ask for the rate. Ask for section A. Ask for the break-even timeline on any points being charged. Those three questions together tell you what the loan actually costs.
Follow Chris Barnes for more transparent guidance on mortgage strategy and protecting your family’s financial future from day one.
Sources
ConsumerFinancialProtectionBureau.gov
FannieMae.com
MortgageNewsDaily.com
Investopedia.com
BankRate.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Start your application with Chris Barnes at Novus Home Mortgage. It takes about 10 minutes and there is no obligation.
Apply NowCheck your inbox for the full breakdown. Chris will follow up if you have questions. Ready to move forward? Apply now.

